Seller Concessions: When They Make Sense
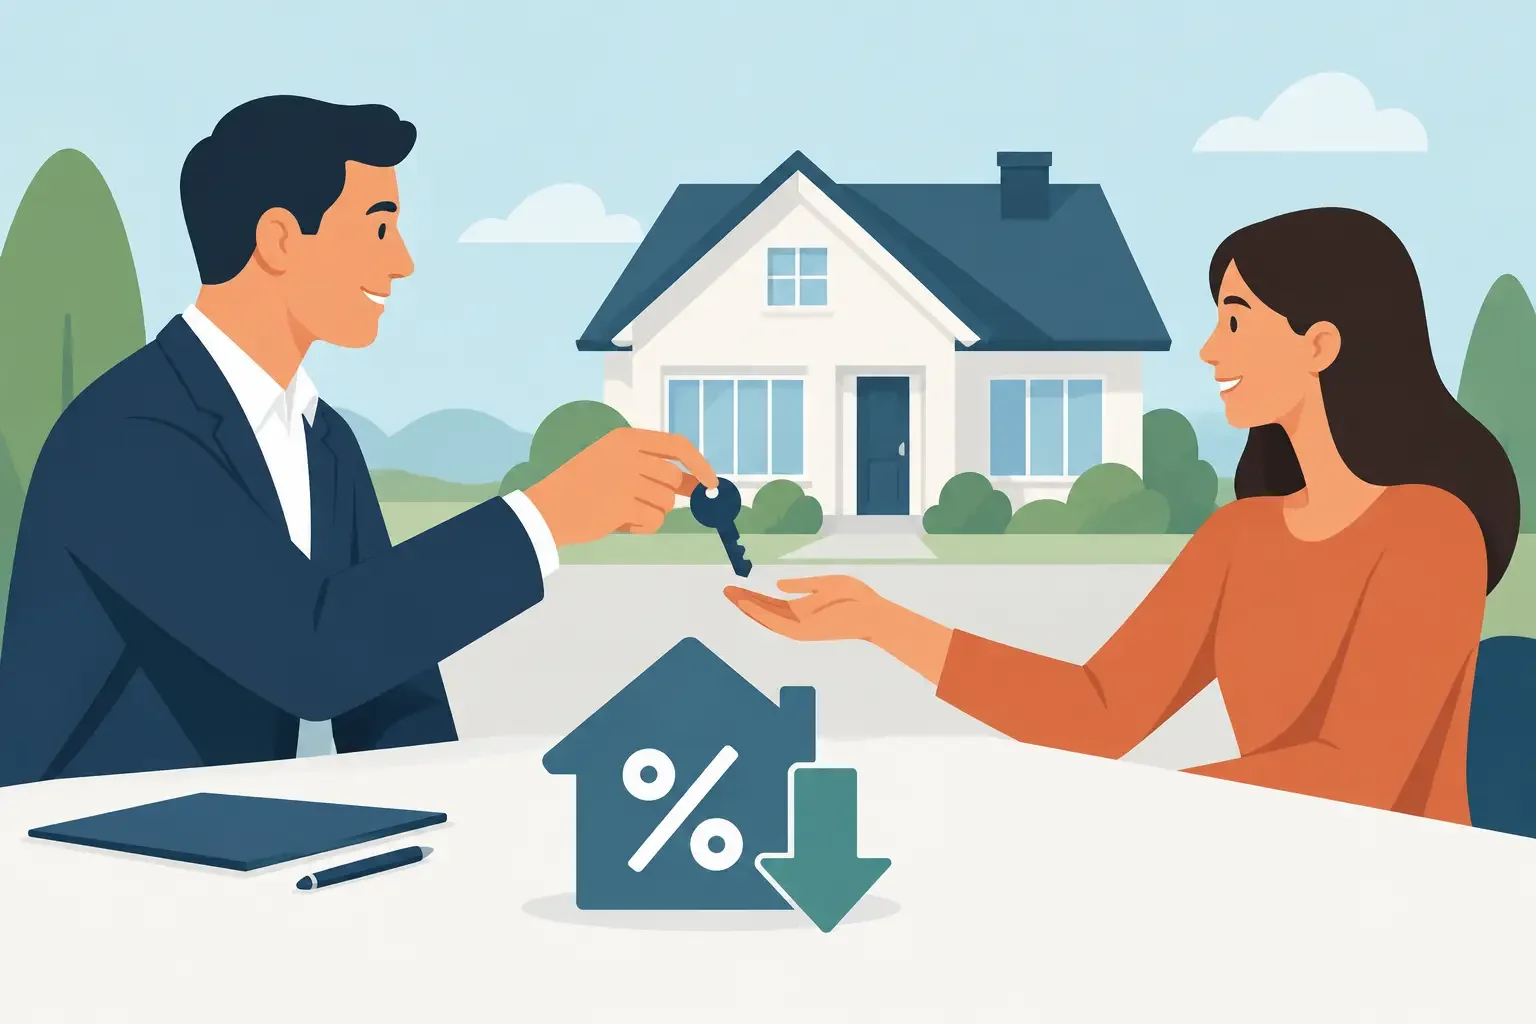
A buyer loves your home, the offer price is solid, and the financing is in place - but they ask for $20,000 in seller concessions. That request can feel like a costly surprise. In the right situation, though, seller concessions can be the detail that gets a well-qualified buyer to closing without weakening the value of your sale.
The key is to look beyond the credit amount. In the Mid-Peninsula and broader Silicon Valley market, concessions should be evaluated alongside the offer price, financing terms, appraisal risk, inspection findings, closing timeline, and the strength of competing interest. A credit is not automatically a bad deal, nor is it a reason to accept an otherwise weak offer.
What Are Seller Concessions?
Seller concessions are costs the seller agrees to pay on a buyer's behalf as part of the purchase agreement. The money is generally applied through escrow at closing, rather than handed directly to the buyer. Depending on the loan program and transaction structure, the credit may cover eligible closing costs, prepaid expenses, discount points used to reduce the buyer's mortgage interest rate, or certain repair-related costs.
In practical terms, a buyer may offer your asking price but request a credit to offset the cash they need to close. For a buyer who has made a substantial down payment, paid for inspections, and covered moving costs, that assistance can make the transaction more manageable.
The lender has an important role here. Loan programs set limits on how much a seller may contribute, and the lender must approve what the credit will cover. A concession cannot simply become cash back to the buyer. If the buyer's allowable closing costs are lower than the agreed credit, some or all of the unused amount may be lost unless the terms are revised before closing.
Why a Buyer Requests a Seller Concession
A concession request does not necessarily mean the buyer cannot afford the property. It may reflect a financing strategy, particularly when mortgage rates make monthly payments more expensive than they were a few years ago. A buyer may prefer to preserve cash reserves, buy down their rate, or cover legitimate closing expenses rather than bring every available dollar to the table.
Other requests arise after inspections. In older Bay Area homes, it is common for inspections to reveal deferred maintenance, drainage concerns, roof wear, aging plumbing, electrical updates, or recommendations related to seismic safety. A buyer may ask for a credit rather than require the seller to complete work before closing.
A closing credit can be cleaner than coordinating repairs under a deadline. The buyer can choose the contractor, manage the scope after taking ownership, and avoid last-minute disputes over whether a repair was completed to their satisfaction. That said, a credit should be based on a reasonable understanding of the issue, not a vague attempt to reopen negotiations.
When Seller Concessions Can Be a Smart Move
The best decision depends on the full offer, not the concession in isolation. A $15,000 credit attached to an exceptionally strong offer may be more attractive than a no-credit offer with a lower price, a long contingency period, or uncertain financing.
Seller concessions can make sense when they help preserve a transaction that is otherwise well structured. This is especially true when the home has been properly prepared, priced with current competition in mind, and the buyer has demonstrated serious intent.
They are often worth considering in four situations:
The buyer's offer has a strong price, substantial down payment, reliable lender, and favorable timing.
Inspection results identify a legitimate issue that is easier to address with a credit than through pre-closing repairs.
The buyer plans to use the credit for a lender-approved rate buydown that improves their qualification or payment comfort.
The property has been on the market long enough that retaining an interested, qualified buyer is more valuable than restarting the sales process.
In a multiple-offer setting, the calculation changes. A seller may have little reason to grant concessions if another buyer offers similar or better terms without them. Even then, the strongest offer is not always the highest number. A buyer with cleaner contingencies, stronger financial documentation, and flexibility around the seller's move-out date may justify closer consideration.
Price, Appraisal, and Net Proceeds Matter More Than the Credit Alone
Sellers sometimes respond to a credit request by raising the purchase price by the same amount. For example, a buyer might offer $2,000,000 with a $20,000 seller credit, rather than $1,980,000 with no credit. On paper, the seller's net price may look similar.
But the home still needs to appraise. If the appraised value does not support the higher contract price, the buyer and seller may need to renegotiate, the buyer may need to bring in more cash, or the financing could be at risk. This is particularly relevant when comparable sales are limited or a property has features that are difficult to value, such as extensive renovations, a large lot, an accessory dwelling unit, or a highly specific location advantage.
It is also worth calculating the real net. A higher price can affect transfer taxes, commission, and other transaction costs. The difference may be modest, but decisions should be based on a complete estimated seller net sheet, not a headline sale price.
For sellers, the question is straightforward: after the credit and every related cost, what do you receive, how certain is the closing, and what is the cost of walking away from this buyer? A well-advised negotiation makes those trade-offs visible before you respond.
How to Negotiate Seller Concessions Without Giving Away Too Much
A concession request is a negotiating point, not an instruction. You can accept it, decline it, reduce it, tie it to a higher price if appraisal support is realistic, or ask the buyer to improve other terms.
The most effective response begins with specifics. If the credit follows inspections, request the relevant reports, estimates, and a clear explanation of the concern. If it is intended for closing costs or rate buydown points, confirm the buyer's loan structure and the lender's limits. A vague request is harder to assess and easier to overpay.
Sellers should also watch for a common mismatch: a buyer requests a large credit but has limited actual closing costs to apply it toward. Confirming lender approval early helps prevent an eleventh-hour scramble to restructure the deal.
Timing matters as well. A request made before the offer is accepted is simply part of the original negotiation. A request made after contingencies are removed carries a different weight than one made during an active inspection or loan contingency period. The contract deadline, the buyer's contractual rights, and the quality of the evidence should guide the response.
There are cases where making repairs is the better option. Health and safety issues, lender-required repairs, or defects that would likely concern every future buyer may be worth correcting. For cosmetic items, minor wear, or work a buyer prefers to customize, a credit can be more practical. The right answer depends on the home, the scope of work, and how much disruption a repair would create before closing.
Preparation Creates More Negotiating Room
The strongest defense against unnecessary concession requests begins before the home goes live. Thoughtful property preparation, transparent disclosures, targeted repairs, and a pricing strategy grounded in current local demand reduce surprises and build buyer confidence.
That does not mean every home needs a major renovation. It means identifying which improvements will improve marketability, which issues should be disclosed and priced appropriately, and which projects are unlikely to deliver a return before sale. A pre-listing inspection can be useful in some cases, particularly when it allows a seller to address known concerns on their own schedule rather than under pressure from a buyer's contingency timeline.
Clear presentation matters too. When buyers understand the condition of the home and can see the care behind it, they are less likely to assume every unknown is a costly problem. Preparation gives sellers more control over the narrative and more confidence at the negotiating table.
At Clutch Property, that work is part of helping clients feel taken care of from preparation through closing. The goal is not to avoid every buyer request. It is to enter negotiations with the information, presentation, and strategy to decide what truly serves your outcome.
A seller concession should earn its place in the deal. When it protects a strong contract, solves a real issue, and supports a reliable close, it can be money well spent. When it masks weak financing, exceeds the buyer's legitimate costs, or gives away leverage without improving the terms, it deserves a careful counteroffer. Before responding, ask for the full financial picture - then make the decision that keeps your sale moving on the right terms.